Corporate Bonds vs Government Bonds

Corporate and government bonds trade side by side on the Ghana Fixed Income Market (GFIM). Both are listed on the same platform, cleared through the same Central Securities Depository, and quoted to the same investor base. But sharing a market does not mean sharing a risk profile. The risks behind a Government of Ghana (GoG) bond and the risks behind a corporate note from an issuer like Petrosol Platinum Energy PLC (Petrosol) or Bayport Savings and Loans rest on entirely different foundations, and that difference shapes how investors size and price each position.

The Basic Difference

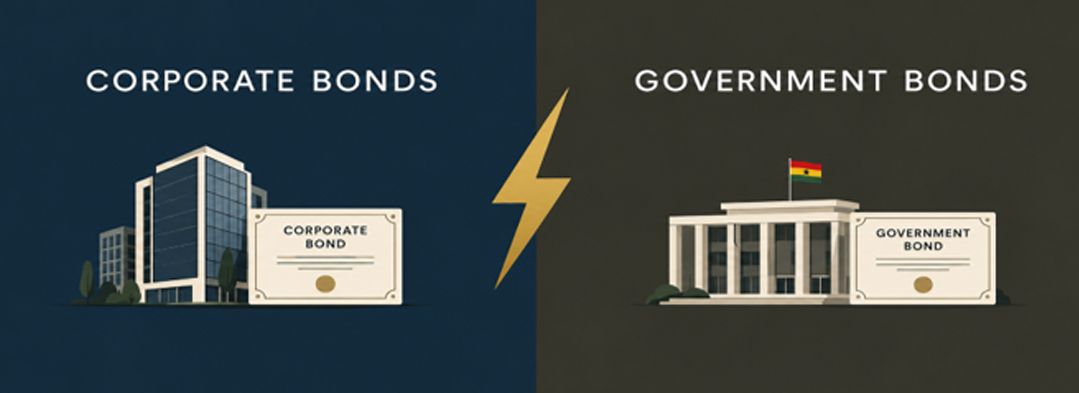
A corporate bond is a loan to a company. A government bond is a loan to the government. Both promise to pay you interest and return your money at maturity. The difference is who is on the hook if things go wrong.

Why Corporate Paper Pays More

In August 2026, Petrosol issued a GH¢50 million bond on GFIM at a 16.25% coupon, maturing in 2030. Then in September, the government issued a similar 4-year bond at a 12.00% coupon. That gap, about 4.25 percentage points, is the market’s premium for holding corporate bonds. The coupon premium on corporate paper compensates for several risks that sovereign bonds do not carry in the same form. These include:

  1. Credit Risk: This is the main risk that distinguishes corporate bonds from government bonds. Credit risk is the risk that a borrower will not repay what they owe, so the lender loses money. Both bonds carry credit risk, but the risk is higher for corporate issuers. Petrosol is a single company. Its ability to repay depends on its operations, its profitability, cashflows and management decisions. The government’s ability to repay depends on the entire economy, tax and other revenue sources and access to domestic and external financing. Investors demand extra compensation for taking on that narrower, company specific risk from an issuer like Petrosol or other companies.
  2. Liquidity Risk: Liquidity risk is the risk that you cannot sell a bond quickly without taking a lower price because few buyers are active on the market. With corporate securities making up roughly one percent of traded volume, secondary market depth is thin. An investor who needs to sell a corporate bond before maturity may struggle to find a buyer and may have to accept a lower price, a risk that government bond, which is the dominant and most actively traded instrument on GFIM, does not carry to the same degree.


  3. Disclosure and Transparency: Government issuance is backed by public fiscal data, IMF programme reporting, and budget disclosures that are, continuously available to investors. Corporate issuers on GFIM vary widely in the depth and frequency of their financial disclosure, which makes credit assessment more labour intensive and less standardised across different names.
  4. Market Depth: The corporate segment of the market remains concentrated among a small set of repeat issuers, largely in savings and loans. There are only a few corporate bonds to choose from, so investors cannot diversify their investments. Investors therefore take on the credit risk of a few specific issuers, so a single default can weigh heavily on returns.

Government Bonds Are Not Risk Free Either

Based on the above, it is tempting to treat sovereign bonds as completely safe. Ghana’s own recent history says otherwise. The Domestic Debt Exchange Programme (DDEP) restructured government bonds, replacing existing securities with new ones carrying lower interest rates and longer maturities, so investors received less than they had originally expected. Government risk is lower than most corporate risks, but it is not zero!

Who Is Actually Issuing Corporate Bonds

The corporate side of GFIM is small and concentrated. Ghana Cocoa Board alone accounts for GH¢7.33 billion of the GH¢8.45 billion in outstanding corporate securities. Beyond COCOBOD, the remaining issuers are Letshego Ghana, Bayport Savings and Loans, Izwe Savings and Loans, Kasapreko Company, Petrosol Platinum Energy and Quantum Terminal Plc.

What This Means for an Investor

A higher coupon on a corporate bond is not free money. It is compensation for real risk that government paper does not carry in the same way. Before buying corporate debt, it is worth asking a few simple questions: How much debt does this company already have? Are its profits and cashflows stable and sufficient enough to repay the bond? What happens to bondholders if it cannot pay?

Government bonds carry default risk, tied to the government’s finances. Corporate bonds carry issuer risk, tied to one company’s finances, and therefore pay a premium for that risk. Same market, same basic structure, genuinely different risks sitting underneath the yield.

The Tax Everyone Pays

A Familiar Story

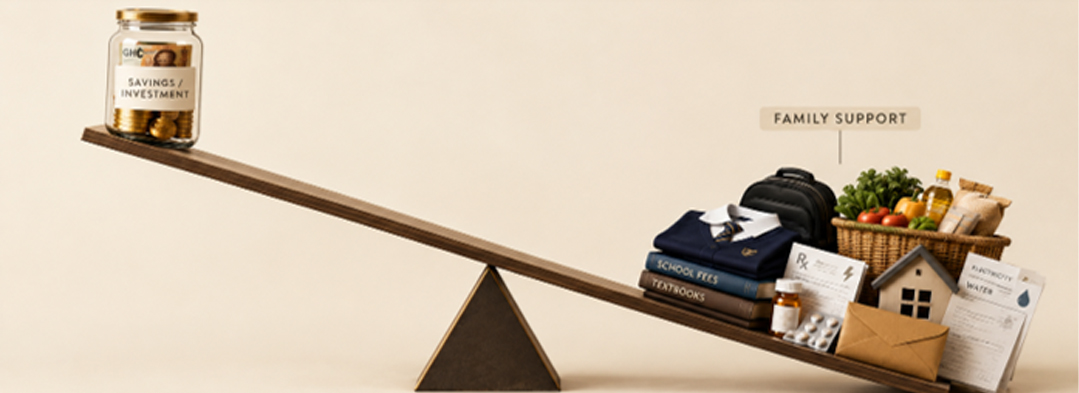
A young professional gets a job, promotion, moves abroad, or simply starts earning steadily above the household average. Within months, the phone calls change. School fees for a cousin. A hospital bill for an uncle. Rent for a sibling. A contribution toward a wedding, then a funeral, then another wedding. None of these requests feel unreasonable on their own. Together, over years, they quietly become the largest unbudgeted expense in that person’s financial life.

This is black tax. It refers to an informal financial obligation where working adults give a portion of their income to support parents, siblings, and extended family on an ongoing basis. Black tax is prevalent in Ghana and across Sub-Saharan Africa because the state does not provide enough social support, so families lean on whoever is earning. On top of that, culture makes family support feel like a duty, not a choice.

When Success Creates a Queue, Not Freedom

In our settings, success does not always create freedom. Often it creates an endless queue. The day you “make it”, everyone suddenly remembers your number. Before long you are financing lifestyles you were never responsible for. You are solving crises that never end. Not because you are wealthy, but because you are afraid of disappointing people. And your own line items keep waiting. Your retirement waits. Your investments wait. Your children’s education fund waits. Your emergency fund waits. Because everyone else’s urgency becomes more important than your own.

Saying NO becomes difficult because you do not want to be called proud or stingy. You do not want anyone saying you forgot where you came from. So you hand out money that should have gone into an investment account, and call it family duty.

The Real Cost And Danger

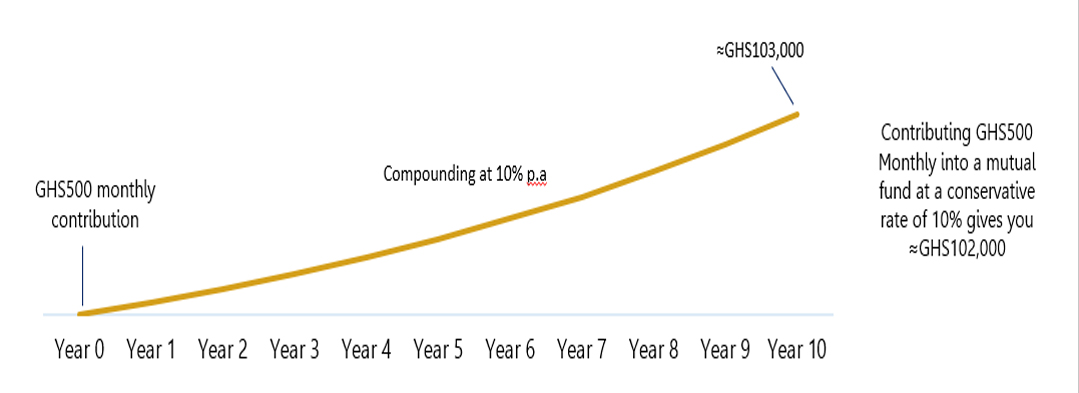
The interesting part of black tax is not the emotional dimension. It is the opportunity cost. A professional supporting several relatives with GHS500 to GHS1,000 a month, over ten years, gives up six figure capital that could have gone into a pension, mutual funds, or a business. That gap only grows wider with time and the power of compounding.

The real danger shows up when income stops, through job loss, a slow business, illness or even retirement. That is when the missing buffer becomes obvious. And the relatives who were once supported usually cannot help in return, not because they are ungrateful though they sometimes are, but because they are stretched just as thin.

Give With A Budget, Not A Blank Cheque

None of this argues against supporting family. It argues for treating family support the way any disciplined household treats a recurring liability: budgeted, bounded, and reviewed. Here are a few principles worth applying:

  • Set a defined, budgeted amount for family support each month, the same way you would budget for any other recurring expense. Communicate boundaries clearly and early. Clear expectations reduce resentment on both sides.

  • Protect retirement contributions, emergency funds, and investment commitments as non negotiables that come before discretionary family support, not after it.

  • Separate a genuine emergency for a family member from a recurring lifestyle subsidy. One deserves a response. The other deserves a boundary.

  • Teach dependents to build their own income streams instead of becoming their permanent solution. That is a better long-term gift than any single cash transfer.


The Legacy Worth Building

Black tax will likely remain a feature of Ghanaian family life for the foreseeable future. The financially sound response is not to withdraw from family obligation, but to bring the same discipline to it that any serious investor brings to every other financial decision.

The most durable form of generational wealth is not the ability to rescue every relative in every crisis. It is a family that eventually needs fewer rescues, because someone in an earlier generation chose to build capacity and capital rather than dependency.

——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

From Bonds to Stocks, The Post‑DDEP Investor Migration

Understanding the capital market

The financial market is ever evolving yet remains structured to cater to the needs of investors. For people who want to invest and still have their money close to their purse, the market provides such opportunities for investments in near-cash securities. These forms of investments are classified under the Money Market. Conversely, there is the Capital Market which is more suited towards investors who do not mind having their funds locked in selected assets (typically equity investments) beyond a year.

Changing equity market dynamics?

Slowly, we see the equity market in Ghana being treated as a money market space for short-term, low-risk high-reward investments. Demand for stocks on the Ghana Stock Exchange has increased significantly, following the rough patch faced by some investors during the Domestic Debt Exchange Programme (DDEP). The road to economic recovery, paved with commitment to fiscal discipline and debt management largely shifted investor attention from the fixed income market (due to falling rates) to the stock market as soon as the rally of the latter began. The market moved favourably towards the stock market and investors followed. However, the motivation to participate in equity market boom is what seems concerning. For most retail investors, the stock market is simply a price war where the more fortunate prevail.

Time in the market Vs Timing the market

Whenever the conversation on investment is tabled, time factor and its contribution to achieving financial goals is inevitable. Usually, the amount of time an investor spends in the stock market literally pays dividends. While exceptions to this exist, it is almost unlikely to successfully and consistently time the market always as indicated by John Bogle. “Only liars claim they are always out during bad times and in during good times” – Bernard Baruch.

Price Watching Vs Business Watching

The fear of missing out and anxiety around price movements on the stock market often results in buy and sell orders that are neither planned nor measured. Investors are constantly on edge by the ups and downs on the market. Warren Buffet famously noted that in the short run, the stock market is a voting machine, but in the long run, it is a weighing machine.

The voting polls scarcely favour the unpopular and uncharismatic and we see a similar phenomenon on the stock market where investor demand for a stock skyrocket with growing market sentiment and popularity with little to no consideration of the fundamentals of the company. In the long run, the underlying fundamentals of the stock show its true value. The weighing machine shows what value is fair, not influenced by speculation, anxiety and general market sentiments. It focuses on revenue, profitability and ultimately the intrinsic value of stocks on the market.

Navigating Market Noise

The big question is how to navigate the market and stay grounded amidst market hype. It is important to know that not every price movement requires a response by an investor.

Start with a financial goal and a suitable plan to achieve that goal. Stay on track even when the market says otherwise especially when your decision is only motivated by the public opinions.

With the stock market, sometimes being the patient investor beats being an active investor whose entire goal is to successfully time the market consistently based on price movements.

Set an allocation specifically for equity investments, whether lump sums and periodic outflows. Preferably, these should be funds you do not need to liquidate quickly.

Finally, when in doubt, seek professional advice to ensure your financial goals are met.

——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

Strategic Asset Allocation

Overview

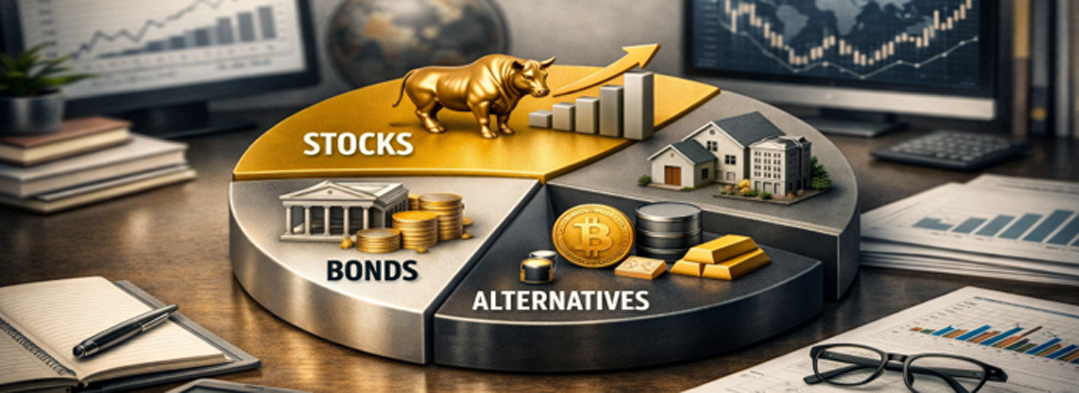
Strategic Asset Allocation (SAA) defines the long‑term mix of asset classes, such as equities, fixed income, and cash, to meet an investor’s goals within their risk tolerance and time horizon. It builds a disciplined framework that balances risk and reward through diversification and consistency rather than reacting to short‑term market movements. SAA should be reviewed periodically and documented in a clear investment policy statement.

Key Considerations

Risk Appetite: This is essentially the amount of risk you are willing and able to take on in pursuit of your financial goals. It reflects both your comfort level with uncertainty and your capacity to absorb potential losses without abandoning your investment plan. Conservative investors favor bonds and cash; aggressive investors lean toward equities.

Investment Horizon: Your horizon will inform the class of assets to invest in. For instance, longer horizons (10+ years) allow for higher equity exposure since short-term volatility can be absorbed.

Liquidity Needs: Consider how much of your portfolio must remain liquid for near-term expenses. Illiquid assets (private equity, real estate, infrastructure) may offer higher returns but can’t be easily sold in emergencies

Benefits

Risk Reduction: Diversification across asset classes limits exposure to any single market and smooths volatility.

Return Enhancement: Combining different asset classes like equities, bonds, real estate and others, creates multiple income streams and a resilient return profile.

Behavioural Discipline: A structured plan prevents emotional reactions to market swings and supports long‑term wealth building.

Cost Efficiency: SAA allows for fewer trades and less market timing which reduce transaction costs and improve net returns.


Rebalancing Portfolio 

As an investor, rebalancing your portfolio maintains alignment between portfolio composition and target risk profile. It involves selling overweight assets and buying underweight ones to preserve discipline, lock in gains, and control losses. The process includes assessing weights, setting thresholds, adjusting strategies, executing trades, and monitoring continuously. This can be done annually or quarterly if necessary.

Risk and Trade‑Offs 

SAA manages trade‑offs intelligently rather than eliminating risk.

Over‑Diversification: While diversification reduces risk, excessive spreading can make the portfolio inefficient and harder to manage.

Illiquidity: Some investments like real estate or private equity tie up capital. They can’t be sold quickly, which limits flexibility when you need cash or want to rebalance.

Market Volatility: Even a well‑allocated portfolio experiences short‑term swings. Investors must tolerate these fluctuations without abandoning their long‑term plan.

Opportunity Cost of Safety: Holding too much in low‑risk assets can protect capital but may limit growth potential. The trade‑off is between security today and wealth accumulation tomorrow. Finding a balance is key.

Currency & Geopolitical Exposure: Diversifies returns, potential gains from favorable FX moves and provides Access to growth in emerging/frontier markets. However, there is potential losses from adverse FX shifts, political instability, etc.

Typical Allocation 

Asset mix evolves with age and financial needs. Our financial needs and profiles differ as we go through life. We need to ensure that we have the right balance at any point in time.

Strategic Asset Allocation is the foundation of disciplined investing. It emphasizes long‑term planning, diversification, and periodic review to achieve sustainable growth while managing risk intelligently.


——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

When There’s Blood On The Streets

The phrase “buy when there is blood on the streets” sounds intense, but it is one of the most powerful concepts in investing. Originating centuries ago, from the banking giant Baron Rothschild, it describes a market in total chaos. It means asset prices are crashing, headlines are apocalyptic, and everyday investors are panicking and selling everything they own out of pure fear.

It is during these exact moments, when the streets are “bloody” that the absolute best buying opportunities are born. As Warren Buffett famously put it: “Be fearful when others are greedy, and greedy when others are fearful”. When the market panics, stock prices separate from their actual, real-world value. For the disciplined investor, these moments of maximum panic aren’t a signal to run away but the ultimate time to buy.

There is, however, a rule to this strategy: you don’t just double down on any random investment. Buying a failing company just because it is cheap is a quick way to lose your capital. When there is blood on the streets, your goal is to buy only the highest quality investments; businesses with rock-solid fundamentals that are temporarily on sale due to market-wide fear.

The Math of the Margin of Safety

Margin Of Safety is the difference between what an investment is worth (value) and what an investor pays to own it (price), and every investment comes down to price versus value. When others are greedy, prices skyrocket far above what companies are intrinsically worth, which shrinks your future profits and your margin of safety.

In contrast, when panic sets in, frantic selling forces high-quality assets into deep discounts increasing your margin of safety in the process. Buying when everyone else is selling gives you a lower cost basis. Purchasing more shares at a lower price drops your average cost per share accelerating your path to profitability the moment the market (inevitably) bounces back.

Separating the Gems from the Junk

Leaning into a market crash does not mean gambling on speculative stocks or on struggling companies that might not survive. To win during a downturn, you must filter out the noise and focus strictly on quality. Before you deploy more cash into an asset during a crisis, it must check these boxes:

♦ A Strong Balance Sheet: The company must have plenty of cash and low debt so it can weather economic storms without going bankrupt.

♦ Resilient Cash Flow: Look  out for businesses providing products or services that people will demand irrespective of the state of the economy.

♦ A Lasting Competitive Advantage: The business should have a strong brand, unique technology, or high barriers to entry that protect it from competitors.

When a market-wide crash happens, excellent companies get dragged down right alongside failing ones. Your job is to identify the elite businesses that are being unfairly punished by the crowd’s panic.

Distinguishing Volatility from Permanent Loss

To successfully buy when others are afraid, you must understand a crucial distinction: short-term price swings are not the same as permanent risk.

Volatility is the temporary, dramatic movement of stock prices driven by bad headlines, fear, or heavy trading. Permanent loss of capital happens when a business breaks completely, goes bankrupt, or when an investor panics and sells at the absolute bottom, locking in their losses forever.

If a top-tier company’s balance sheet is strong, its cash flows are intact, and its long-term business remains solid, a crashing stock price is simply a holiday sale.

Wealth isn’t made by following the crowd; it is transferred from the impatient and fearful to the patient and disciplined during times of crisis.

The Verdict: Fortune Favors the Uncomfortable

Buying when the future looks bleak is deeply uncomfortable. It goes against every natural human instinct to move away from the crowd. Your screen will be red, the news headlines will be terrifying, and everyone around you will tell you that you are making a mistake.

But historically, the absolute best times to build an investment portfolio are born during recessions and market crashes. To buy during bad times and recessions is to take advantage of times and seasons. There will always be good times after bad times and bad times after good times.

Finally, to buy in bad times is to bet on a positive and better future, but a note of caution to investors who plan to use this strategy: always bet that things will go well in the long run, but not so aggressively that you get wiped out in the short run


——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

How Young Ghanaians Can Start Building Wealth Today

Many young people view money primarily as something to spend; whether on lifestyle expenses, trends, entertainment or short-term wants. While there is nothing wrong with enjoying the money you earn, building long-term wealth requires learning how to make your money work for you and this is where investing comes in.

There is a widely held belief that investing is reserved for older, financially established individuals, but this could not be further from the truth. A popular quote says, “the best time to invest was yesterday, the next best time to invest is now.”  By starting young, you give yourself the advantage of time: time to learn, time to recover from mistakes, and time to grow your wealth gradually through consistent investing.

The good news is that you do not need thousands of cedis to begin your investment journey. With as little as GH¢100, you can take your first step from simply spending money to building long-term financial security. In this blog post, we will highlight some important steps to help you begin your investment journey.

Step 1 – Build an Emergency Fund

Before you begin investing, it is important to first build an emergency fund. This serves as a financial safety net, providing readily accessible cash for unexpected events such as medical emergencies, job loss, urgent home repairs, or other unforeseen expenses. Having an emergency fund in place reduces the likelihood of having to liquidate your investments at an unfavorable time, allowing your investments to remain focused on achieving your long-term financial goals. As a general rule, aim to save enough to cover three to six months of essential living expenses before committing significant amounts to investments. This foundation can help you invest with greater confidence and financial stability.

Step 2 – Define Your Investment Goals

Ask yourself what your reason for investing is and when you will need the money. Whether your goal is postgraduate studies, buying a car, purchasing a home, or building long-term wealth, your investment objective and timeline should guide your investment decisions. For short-term goals, lower-risk options such as Treasury Bills and money market funds may be suitable. For longer-term goals, investments such as mutual funds, stocks, and pension products may offer higher growth potential.

Step 3 – Explore Investment Options

Ghana offers a variety of investment opportunities, including Treasury Bills, Collective Investment Schemes (mutual funds and unit trusts), Fixed Deposits and Stocks. Each option carries a different level of risk and return, so investors should select products that align with their goals and risk tolerance. Generally, lower-risk investments such as Treasury Bills and fixed deposits offer more stable but lower returns, while higher-risk investments such as stocks provide greater return potential in exchange for increased risk.

Step 4 – Open an Investment Account

Most investment firms will require a valid Ghana Card, proof of address, next-of-kin information, and an initial deposit to open an investment accounts. Many institutions now offer digital account opening, making the process quick and convenient.

Step 5 – Invest Consistently

You do not need a large amount to begin investing; what matters most is consistency. Setting aside a small, manageable amount each month, even as little as GH¢50, can be powerful over time. The key driver behind this is compound interest, where the returns you earn on your investments begin to generate their own returns as time passes. This creates a ripple effect, meaning your money grows faster the longer it remains invested. By contributing regularly and allowing your investments time to compound, you steadily build wealth without needing large initial capital.

Remember, successful investing is not about how much you start with; it is about starting early, staying disciplined, and allowing time and compounding to work in your favour.

Contact us today to begin your investment journey.


——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

Learn the Language, Win the Game

Terms like stocks, bonds, and treasury bills often come up in conversations, yet many young people feel unable to engage due to limited financial literacy. These concepts, however, are important when building long‑term wealth. While investing is often perceived as complex, it becomes far more approachable once you understand the language. For young individuals eager to begin their investment journey, here are 10 key terms that provide a solid foundation and enable meaningful participation in financial discussions:

1. Investment: Making an investment means using money today to grow its value in the future. It involves putting money into different assets to reach a goal and/or attain long‑term wealth. For example, if you buy a 1-year Government Note with GH¢500 at an interest rate of 15%, you will earn GH¢75 in interest. At the end of the period, your money grows to GH¢575 (GH¢500 + GH¢75 interest). This isn’t magic, it is the power of investment. An investment turns today’s money into tomorrow’s growth.

2. Compound Interest: This is the money that is earned on both your original investment and on the interest that you earn; it makes your money grow faster over time. Compound interest is calculated as: Your money × (1 + interest rate)years.
In simple terms, it means that
Year 1: You earn interest on your initial investment.
Year 2: You earn interest on both your initial investment and the interest from year 1.
Year 3: You earn interest on your initial investment and the interest earned in years 1 and 2. Compound interest can dramatically increase your growth potential and help you reach your financial goals quicker.

3. Portfolio: A portfolio is the total collection of investments owned by an individual or an organization and can include asset classes such as stocks, bonds, treasury bills, and mutual funds. Think of it as a big basket where all your investments are held together.

4. Risk Tolerance: Risk is the chance that an investment’s outcome will be different from what you expect. Risk tolerance is how much risk an investor is comfortable taking when making investment decisions. It helps financial advisors match investments to an investor’s long‑term objectives. Some investors have a high-risk tolerance and are willing to take bigger risks for potentially higher returns, while others have a low risk tolerance and prefer safer, more stable investments.

5. Inflation: Inflation is the gradual rise in the prices of goods and services over time.  This reduces the purchasing power of money, meaning the same amount of money buys fewer things than before. For example, if a pen costs GH¢5 today, you can buy 10 with GH¢50. But if the price rises to GH¢8, that same GH¢50 can no longer buy 10 pens.

This is why investors aim to earn returns that are higher than the inflation rate, so their money grows faster than prices increase.

6. Liquidity: Liquidity is how quickly and easily an investment or asset can be turned into cash without losing value. Highly liquid assets can be sold or accessed right away. Examples include treasury bills, money in a savings account and cash itself (the most liquid asset since it can be used immediately).

7.  Shares (Stock): Shares represent units of ownership in a company; when you buy shares, you own a small part of that company. Investors can make money from shares in two main ways:

Capital gains: When you buy a share at one price and later sell it at a higher price, the difference is your profit (or capital gain)

Dividends: These are the portions of the company’s earnings that it distributes to its shareholders. As a company’s earnings grow, dividends may also increase proportionally

8. Bond: A bond is an investment where an individual lends money to the government or a company for a set period in return for regular interest payments. At the end of the agreed term, the original amount (principal) is repaid to the investor. Bonds are generally considered lower‑risk compared to stocks, making them a more stable option for conservative investors.

9. Bull and Bear Markets: A bull market is when stock prices are rising, and investments are expected to grow. It usually reflects strong economic conditions and investor confidence. A bear market, on the other hand, is when stock prices are falling and investments are losing value. In this environment, investors often become cautious and less confident about the market.

10. Market Value: Market value is the current price at which an asset can be bought or sold in the market. Simply put, it shows the value that the market places on your investment today. For example, if you own 600 units and each unit is priced at GH¢10, your market value is 600 × GH¢10 = GH¢6,000. This means that if you sell your asset now, you will receive GH¢6,000.

Reaching the end of this blog is an important step toward growing your investment knowledge. Investing is a strategic way to build wealth, and you now have a head start. Now that you understand the basic terms, your next course of action should be to learn how you can begin investing. With this foundation, the process won’t feel as intimidating as before. Start investing today, and your future self will thank you.


——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

Slow and Steady Wins The Race

For over a century, the most reliable path to building wealth in financial markets has not been speed, speculation, or brilliance, but discipline.

Investors who commit to making steady investment contributions, long-term planning, and disciplined strategies have generally achieved more reliable investment results than people who chase short-term trends. This philosophy was championed by John Bogle, who promoted inexpensive index fund investing. He also advocated for long term investing, no matter the fluctuations in the short term, rather than trying to beat the market. There were many people who made mockery of John Bogle when he established the Vanguard Group in 1975 and introduced the first index fund for regular investors. It was referred to as “Bogle’s Folly.” And why? Because Bogle made it his goal to meet the market, at a minimal cost, rather than to beat it. Nearly sixty years later, trillions of dollars have been invested in index funds, and his philosophy has aided millions of investors in accumulating long-term wealth. So, what exactly makes this approach so powerful? Why has it worked through some of the most turbulent financial periods in modern history? The answer is simple: compounding!

The Power of Compounding

At its core, long-term investing is about compounding. It is basically your money having babies, and those babies having more babies. Over time, that growth turns into a massive snowball. An example is the S&P 500, which has historically delivered average annual returns of roughly 9–10% over long periods, including reinvested dividends. While individual years may swing dramatically, decades of steady participation have rewarded patient investors. What makes this powerful is not dramatic spikes, but consistency. A modest investment, left to grow over decades, can multiply significantly. When combined with regular contributions, the effect becomes even more pronounced. Compounding does not demand brilliance; it requires patience.

Diversification

But growth alone is not enough; you also need to protect what you’re building. That’s where diversification comes in. While compounding drives long-term returns, diversification helps manage the risks that come with staying invested over time. By spreading investments across different asset classes and industries, investors reduce the impact of any single underperforming asset. In simple terms, you’re not putting all your eggs in one basket. This makes the overall portfolio more resilient, as different assets tend to respond differently to economic conditions.

Staying the Course Even in Crisis

Even with a well-diversified portfolio, the greatest challenge in investing often lies not in strategy but in behavior—behavioral biases. Patience becomes most difficult and most critical during periods of uncertainty. A recent Ghanaian example is the Domestic Debt Exchange Programme in 2022. The announcement sparked significant anxiety among bondholders, prompting many to exit positions at steep discounts to avoid potential losses. As the process progressed and clarity improved, conditions stabilized. Investors who stayed the course were generally better positioned than those who sold early and crystallized losses. The pattern is consistent: in periods of stress, fear drives premature decisions, while patience supports long-term value preservation.

The Risk of Chasing Trends

Short-term speculation can be tempting, but it often comes at a cost. In 2018, Ghana experienced the collapse of Menzgold Ghana Limited, which had attracted investors with promises of unusually high returns. Many concentrated their funds in the scheme, drawn by its apparent consistency. When operations were halted by the Securities and Exchange Commission Ghana, investors lost access to their funds, with those most exposed bearing the greatest losses. In contrast, diversified portfolios proved more resilient. Chasing “hot” opportunities may seem attractive, but diversification remains the more reliable safeguard.

Investing Is a Marathon, not a Sprint

The metaphor holds true: investing is a marathon. A sprinter might look impressive for the first hundred meters, but endurance is what wins a marathon race. Equity markets globally have endured numerous financial crises, recessions, and geopolitical tensions. Yet long-term trends have remained upward. It is not to say that markets are risk-free; they are not. The lesson is that time, diversification, and discipline reduce risk and enhance opportunity.

Successful investing is less about predicting the future and more about preparing for it. By focusing on consistency, embracing diversification, and maintaining discipline through market cycles, investors can harness the full power of long-term growth. For many, consulting an investment advisor adds another layer of structure, helping investors align investment decisions with long-term goals and risk tolerance, manage risks, and seize opportunities aligned with their goals.

——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

Lower Rates, Higher Stakes: Navigating Securities Markets in an Easing Cycle

As 2026 unfolds, the Ghanaian economy is showing clear signs of macroeconomic stabilization

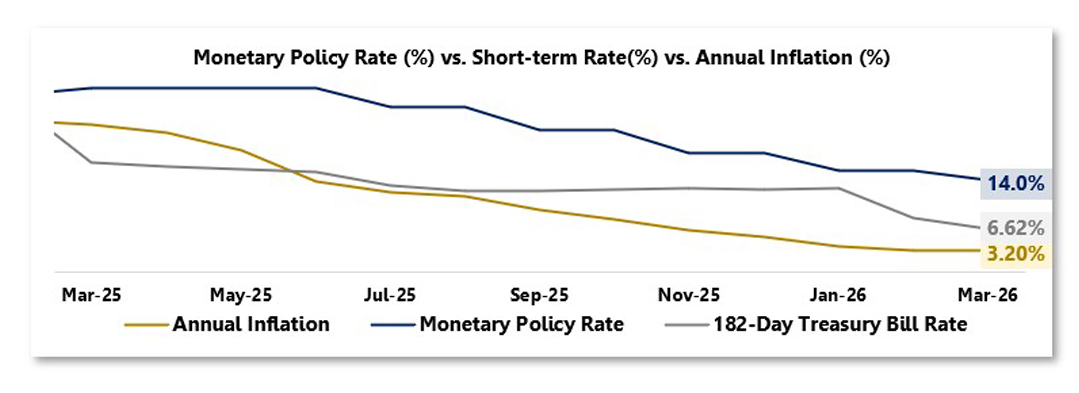
By February, inflation had dropped to 3.3%, extending a fourteen-month disinflation trend from 23.5% in January 2025. Over the same period, the Bank of Ghana reduced the Monetary Policy Rate (MPR) from 18.0% to 15.50%, before a further cut to 14.0% in March, bringing cumulative easing in 2026 alone to 400 basis points. This policy shift reflects improving macroeconomic fundamentals and declining price pressures.

While lower policy rates enhance liquidity and reduce borrowing costs across the economy, they also fundamentally reshape investment dynamics. As risk-free returns compress, investors are increasingly pushed along the risk curve in search of yield. In this environment, the opportunity set expands, but so do the stakes.

The Downward Trend in Treasury Bill Yields

The easing cycle is rapidly repricing Ghana’s Treasury bill market. At the start of 2025, short-term government securities delivered outsized returns, with the 182-day bill yielding above 28%. That window has now closed, and demand dynamics tell the story.

February auctions were heavily oversubscribed by 201.4%, but by March, oversubscription had dropped to just 14.0% as investors began rotating into more competitive opportunities. By the final auction of March 2026, the market turned undersubscribed by 20.14%: a clear signal that prevailing yields are no longer compelling.

For conservative investors, the implication is clear: the era of easy, high risk-free returns is ending. In this environment, attention is gradually shifting toward equities as a more viable source of return.

Equities as the New Return Engine

As fixed income yields compress, capital is rotating into equities in search of higher returns. As Treasury bill yields decline, equities become relatively more attractive, particularly dividend-paying and large-cap stocks capable of delivering positive real returns in a low-inflation environment.

However, this shift also brings greater exposure to market volatility, earnings uncertainty, and potential mispricing. The key question, then, is: How should investors position themselves to navigate this new landscape?

Strategic Positioning in a Lower Rate Environment

The changing rate landscape requires a more deliberate and diversified investment approach:

  1. Selective Equity Allocation

Equities present a compelling avenue for long-term wealth creation, but selectivity is critical. Investors should focus on fundamentally strong companies with strong earnings potential, sound balance sheets, and consistent dividend profiles.

  1. Diversification as a Core Strategy

Portfolio diversification is increasingly essential. Allocating across asset classes, sectors, and maturities can help mitigate downside risk while enhancing return potential. A clearly defined investment objective, risk tolerance, and time horizon remain central to effective portfolio construction.

  1. Exploring Alternative Fixed Income Options

Given a low-interest rate environment, it becomes crucial to explore alternative fixed income instruments such as corporate issuances, commercial paper, and fixed deposits to serve a similar purpose. These instruments can offer competitive yields, portfolio diversification, and improved risk-adjusted returns, although they may come with varying levels of credit and liquidity risk that require careful assessment.

Declining interest rates have reshaped Ghana’s securities market by compressing bond yields, driving capital into equities, and altering investor behavior. While the easing cycle has created opportunities for capital appreciation, it has also increased the consequences of poor allocation decisions.

In a lower-rate environment, the margin for error narrows. Investors who adopt disciplined, well-diversified strategies will be better positioned to preserve real returns and capitalize on opportunities within Ghana’s evolving financial landscape.


——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.

Soft Life vs. Smart Life: The Wealth Conversation the Youth of Ghana are Not Having

For many young Ghanaians, the idea of a “soft life” has become the aspiration: comfort, enjoyment, and visible success. But the more difficult question is: are we building wealth or simply projecting it?

What Does “Soft Life” Really Mean?

Soft life, in simple terms, is about choosing ease over constant struggle. It reflects a desire for comfort, flexibility, and enjoyment without the level of stress that previous generations often endured while working relentlessly. In many ways, it’s understandable that young people want something different. However, in recent years, social media has reshaped the meaning of soft life, shifting the focus from financial freedom to visible consumption. The key difference is this: one is sustained by assets, while the other is funded by income.

Why is This a Problem?

The earning potential of young professionals has increased significantly compared to previous generations. However, many are still missing key elements of sustainable wealth building, including Equity investments, Fixed income instruments, Diversified Portfolios and Long-term planning.

The common pattern is to increase income and scale up spending alongside it, while becoming less consistent with savings and, in turn, delaying investments. In practice, lifestyle upgrades come first, and assets come later, if at all. Over time, investing becomes an afterthought, and for many people, “later” never actually arrives.

So, what’s the solution to the pitfalls of chasing a soft life? The answer lies in aiming for a smart life instead.

What Exactly is a Smart Life?

In short, it’s the less glamorous choice: the unpopular path. It looks like investing before upgrading your car, buying treasury bills before changing your gadgets to the latest release, building an emergency fund before planning the next trip or saying, “not yet” when everyone else is saying “why not?”.

However, it’s not about giving up everything or enduring constant hardship. It’s about finding balance, because a soft life without assets is ultimately unsustainable.


Ghana’s Reality and Why This Conversation Matters

Ghana’s economic environment is dynamic, shaped by currency fluctuations, inflation swings, and global market shifts, all of which affect purchasing power more than many young people realize. Simply holding cash is not enough. Building assets through structured investments and diversified portfolios provides real protection. While consumption is visible in real time, compounding, which truly changes lives, remains unseen. Social media amplifies displays of wealth but rarely shows investment statements, asset allocation choices, compound growth, or long-term planning.

So, What Does Balance Look Like?

Balance is not about rejecting a soft life or enjoyment entirely. It is about funding enjoyment intelligently and diligently. You can still relish Friday nights while consistently building your portfolio. A balanced young professional might invest 20–30% of income before lifestyle upgrades, diversify between fixed income and equities, hold assets in both cedis and foreign currency exposure and build medium-term and long-term strategies.

Ten years from now, today’s choices will have compounded. Will you be funding your lifestyle from your salary or from assets working for you? Soft life offers temporary comfort, but smart life provides sustainable freedom.

The Real Flex Is Not What You Post, But What You Own.


——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.