Corporate Bonds vs Government Bonds

Corporate and government bonds trade side by side on the Ghana Fixed Income Market (GFIM). Both are listed on the same platform, cleared through the same Central Securities Depository, and quoted to the same investor base. But sharing a market does not mean sharing a risk profile. The risks behind a Government of Ghana (GoG) bond and the risks behind a corporate note from an issuer like Petrosol Platinum Energy PLC (Petrosol) or Bayport Savings and Loans rest on entirely different foundations, and that difference shapes how investors size and price each position.

The Basic Difference

A corporate bond is a loan to a company. A government bond is a loan to the government. Both promise to pay you interest and return your money at maturity. The difference is who is on the hook if things go wrong.

Why Corporate Paper Pays More

In August 2026, Petrosol issued a GH¢50 million bond on GFIM at a 16.25% coupon, maturing in 2030. Then in September, the government issued a similar 4-year bond at a 12.00% coupon. That gap, about 4.25 percentage points, is the market’s premium for holding corporate bonds. The coupon premium on corporate paper compensates for several risks that sovereign bonds do not carry in the same form. These include:

  1. Credit Risk: This is the main risk that distinguishes corporate bonds from government bonds. Credit risk is the risk that a borrower will not repay what they owe, so the lender loses money. Both bonds carry credit risk, but the risk is higher for corporate issuers. Petrosol is a single company. Its ability to repay depends on its operations, its profitability, cashflows and management decisions. The government’s ability to repay depends on the entire economy, tax and other revenue sources and access to domestic and external financing. Investors demand extra compensation for taking on that narrower, company specific risk from an issuer like Petrosol or other companies.
  2. Liquidity Risk: Liquidity risk is the risk that you cannot sell a bond quickly without taking a lower price because few buyers are active on the market. With corporate securities making up roughly one percent of traded volume, secondary market depth is thin. An investor who needs to sell a corporate bond before maturity may struggle to find a buyer and may have to accept a lower price, a risk that government bond, which is the dominant and most actively traded instrument on GFIM, does not carry to the same degree.


  3. Disclosure and Transparency: Government issuance is backed by public fiscal data, IMF programme reporting, and budget disclosures that are, continuously available to investors. Corporate issuers on GFIM vary widely in the depth and frequency of their financial disclosure, which makes credit assessment more labour intensive and less standardised across different names.
  4. Market Depth: The corporate segment of the market remains concentrated among a small set of repeat issuers, largely in savings and loans. There are only a few corporate bonds to choose from, so investors cannot diversify their investments. Investors therefore take on the credit risk of a few specific issuers, so a single default can weigh heavily on returns.

Government Bonds Are Not Risk Free Either

Based on the above, it is tempting to treat sovereign bonds as completely safe. Ghana’s own recent history says otherwise. The Domestic Debt Exchange Programme (DDEP) restructured government bonds, replacing existing securities with new ones carrying lower interest rates and longer maturities, so investors received less than they had originally expected. Government risk is lower than most corporate risks, but it is not zero!

Who Is Actually Issuing Corporate Bonds

The corporate side of GFIM is small and concentrated. Ghana Cocoa Board alone accounts for GH¢7.33 billion of the GH¢8.45 billion in outstanding corporate securities. Beyond COCOBOD, the remaining issuers are Letshego Ghana, Bayport Savings and Loans, Izwe Savings and Loans, Kasapreko Company, Petrosol Platinum Energy and Quantum Terminal Plc.

What This Means for an Investor

A higher coupon on a corporate bond is not free money. It is compensation for real risk that government paper does not carry in the same way. Before buying corporate debt, it is worth asking a few simple questions: How much debt does this company already have? Are its profits and cashflows stable and sufficient enough to repay the bond? What happens to bondholders if it cannot pay?

Government bonds carry default risk, tied to the government’s finances. Corporate bonds carry issuer risk, tied to one company’s finances, and therefore pay a premium for that risk. Same market, same basic structure, genuinely different risks sitting underneath the yield.

The Tax Everyone Pays

A Familiar Story

A young professional gets a job, promotion, moves abroad, or simply starts earning steadily above the household average. Within months, the phone calls change. School fees for a cousin. A hospital bill for an uncle. Rent for a sibling. A contribution toward a wedding, then a funeral, then another wedding. None of these requests feel unreasonable on their own. Together, over years, they quietly become the largest unbudgeted expense in that person’s financial life.

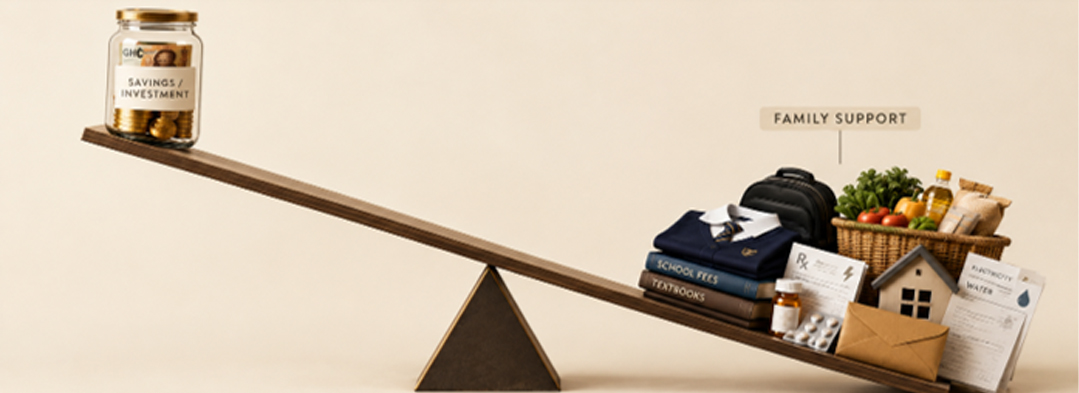
This is black tax. It refers to an informal financial obligation where working adults give a portion of their income to support parents, siblings, and extended family on an ongoing basis. Black tax is prevalent in Ghana and across Sub-Saharan Africa because the state does not provide enough social support, so families lean on whoever is earning. On top of that, culture makes family support feel like a duty, not a choice.

When Success Creates a Queue, Not Freedom

In our settings, success does not always create freedom. Often it creates an endless queue. The day you “make it”, everyone suddenly remembers your number. Before long you are financing lifestyles you were never responsible for. You are solving crises that never end. Not because you are wealthy, but because you are afraid of disappointing people. And your own line items keep waiting. Your retirement waits. Your investments wait. Your children’s education fund waits. Your emergency fund waits. Because everyone else’s urgency becomes more important than your own.

Saying NO becomes difficult because you do not want to be called proud or stingy. You do not want anyone saying you forgot where you came from. So you hand out money that should have gone into an investment account, and call it family duty.

The Real Cost And Danger

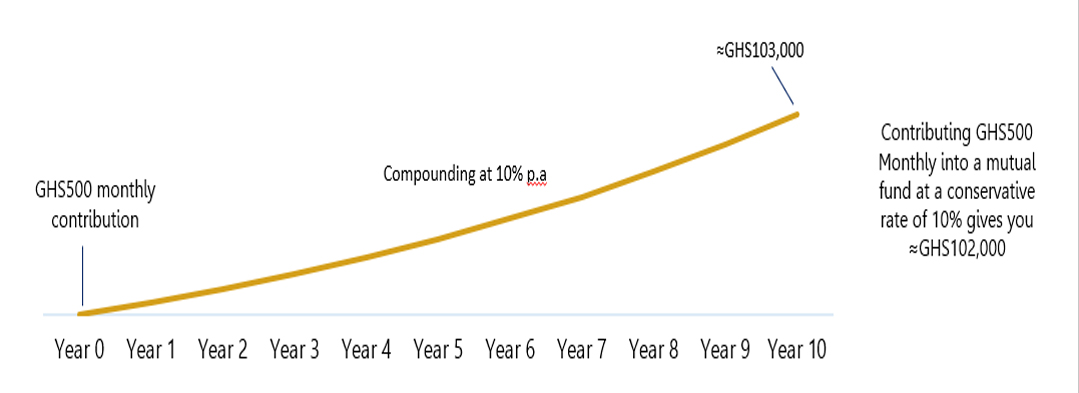
The interesting part of black tax is not the emotional dimension. It is the opportunity cost. A professional supporting several relatives with GHS500 to GHS1,000 a month, over ten years, gives up six figure capital that could have gone into a pension, mutual funds, or a business. That gap only grows wider with time and the power of compounding.

The real danger shows up when income stops, through job loss, a slow business, illness or even retirement. That is when the missing buffer becomes obvious. And the relatives who were once supported usually cannot help in return, not because they are ungrateful though they sometimes are, but because they are stretched just as thin.

Give With A Budget, Not A Blank Cheque

None of this argues against supporting family. It argues for treating family support the way any disciplined household treats a recurring liability: budgeted, bounded, and reviewed. Here are a few principles worth applying:

  • Set a defined, budgeted amount for family support each month, the same way you would budget for any other recurring expense. Communicate boundaries clearly and early. Clear expectations reduce resentment on both sides.

  • Protect retirement contributions, emergency funds, and investment commitments as non negotiables that come before discretionary family support, not after it.

  • Separate a genuine emergency for a family member from a recurring lifestyle subsidy. One deserves a response. The other deserves a boundary.

  • Teach dependents to build their own income streams instead of becoming their permanent solution. That is a better long-term gift than any single cash transfer.


The Legacy Worth Building

Black tax will likely remain a feature of Ghanaian family life for the foreseeable future. The financially sound response is not to withdraw from family obligation, but to bring the same discipline to it that any serious investor brings to every other financial decision.

The most durable form of generational wealth is not the ability to rescue every relative in every crisis. It is a family that eventually needs fewer rescues, because someone in an earlier generation chose to build capacity and capital rather than dependency.

——————————————————————————————————————————————————————————————————————————-

The information contained in this blog is being provided for educational purposes only and does not constitute a recommendation from any Bora Capital Advisors entity to the recipient. Bora Capital Advisors is not providing any financial, economic, legal, investment, accounting, or tax advice through this blog to its recipient.

This report reflects the views and opinions of Bora Capital Advisors Ltd, and is provided for information purposes only. Although the information provided in the market review and outlook section is, to the best of our knowledge and belief correct, Bora Capital Advisors Ltd, its directors, employees and related parties accept no liability or responsibility for any loss, damage, claim or expense suffered or incurred by any party as a result of reliance on the information provided and opinions expressed in this report, except as required by law. The portfolio performance data represented in this report represents past performance and does not guarantee future performance or results.